
A customer accepts a payment plan. The next morning, another team contacts them for the full balance.
Across enterprise portfolios, disconnected systems can leave collectors acting on outdated information. Your accounts receivable (AR) team needs account context that carries across entities and channels.
An AI debt recovery platform can support that coordination by prioritizing delinquent accounts and connecting outreach with self-service payments. However, adopting AI does not automatically create a coordinated recovery operation.
Gartner’s 2025 AI in Finance survey found that 59% of finance leaders reported using AI in their function. Yet 25% remained uncertain about moving from planning to piloting.
Therefore, your buying decision must account for integration and execution alongside the platform’s AI features. This guide explains what makes a platform enterprise-grade, how to evaluate vendors based on evidence, and how to manage phased portfolio rollout. It also shows how to build the business case for your CFO.
What is an AI debt recovery platform for large enterprise AR teams?
An AI debt recovery platform helps enterprise AR teams recover past-due consumer balances through:
- Account scoring and prioritization
- Omnichannel outreach with compliance controls
- Self-service payments
- Dispute and hardship escalation
Instead of relying only on aging buckets, it tailors treatment to each account’s data.
Typical users include banks, auto lenders, fintechs, healthcare providers, utilities, telecoms, subscription businesses, and government agencies. B2B invoice-to-cash automation is a separate category.
Enterprise vs. mid-market requirements
Enterprise and mid-market platforms differ beyond account volume. Governance and compliance reporting both scale up, and procurement shifts from a single department to a cross-functional committee.
| Requirement | Mid-Market Platform | Large-Enterprise Platform |
| Account volume | Single-portfolio, moderate volumes | High volumes across many portfolios |
| Portfolios and entities | One entity, one or two portfolios | Multiple portfolios, brands, and legal entities |
| Volume spikes | Manual workarounds | Absorbs surges without added headcount |
| Access and approvals | Shared admin access | Role-based access with change approvals |
| Customer view | Separate records per tool or vendor | One record across first-party, agency, and recovery stages |
| Reporting audience | AR team | Executives, auditors, board, and regulators |
| Buying process | Single department | Cross-functional buying committee |
The reporting row is the one most buyers underestimate. A platform built for AR managers may track recovery by aging buckets. Enterprise finance leaders need drill-downs by:
- Portfolio and legal entity
- Delinquency band
- Compliance exception type
Audit committees and regulators expect data in formats they can verify.
| Pro tip: Define the recovery goal before the first demo. A clear goal keeps the shortlist focused and prevents vendors from steering the evaluation toward their strengths. |
Which type of AI debt recovery platform fits your AR team?
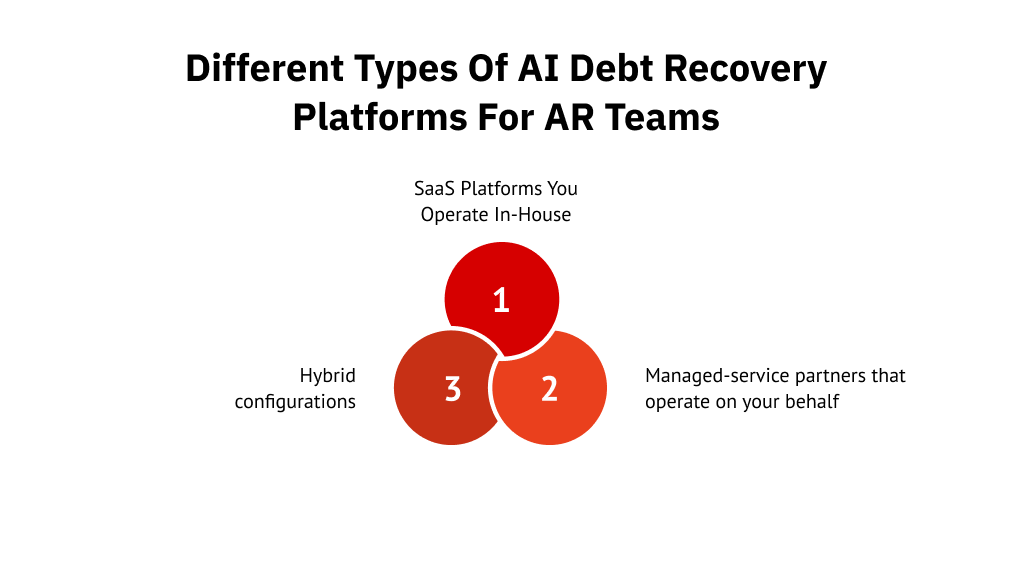
Enterprise recovery platforms use three operating models. The right choice depends on how much your AR team can manage internally and where it needs outside support.
1. SaaS platforms you operate in-house
Your AR team configures scoring, launches campaigns, and monitors results. In return for that control, it must provide analysts, compliance oversight, and IT support.
This model fits teams with established technical resources and policies requiring direct control over consumer-data access.
2. Managed-service partners that operate on your behalf
A partner manages integration, scoring, outreach, compliance monitoring, and reporting. Your team sets strategy and reviews results.
This can support portfolio growth without proportional hiring, provided capacity, responsibilities, and oversight are agreed in advance.
3. Hybrid configurations
When different account stages require different support, a hybrid model splits the work. Your internal team might handle early-stage accounts while a partner takes over at an agreed delinquency threshold or regulatory boundary.
That flexibility depends on a clean handoff. Otherwise, teams using separate systems may send duplicate outreach. Before accounts move, define the transfer trigger, consent-state handover, and suppression rules.
The table below compares the operational requirements of each model.
| Dimension | SaaS (in-house) | Managed service | Hybrid |
| Who operates the platform | Your AR team | The partner | Split by stage or portfolio |
| Staffing requirement | Data science, compliance, and IT | Strategy, oversight, and onboarding support | Varies by split point |
| Volume-spike response | Hire or reassign | Partner scales within agreed capacity | Depends on which side receives the surge |
| Compliance execution risk | Internal | Shared with partner | Split, with documented responsibilities |
| Integration complexity | Your IT manages integrations | Partner configures integrations with your team | May require separate integration tracks |
| Speed to launch | Depends on configuration and staffing | Depends on provider and integration scope | Depends on systems and handoff design |
| Best fit | Large AR operations with dedicated technical staff | Organizations scaling without proportional headcount growth | Programs with distinct early-stage and late-stage recovery needs |
Where First Credit Services helps
At First Credit Services, we operate our proprietary Unified Consumer Engagement Platform (UCEP) on your behalf, combining technology with experienced collections support. Your team sets recovery priorities and reviews performance, while we manage integration, outreach sequencing, compliance monitoring, and ongoing optimization. This helps large enterprise AR teams manage high volumes of accounts without having to manage the technology and day-to-day collection workflows themselves.
Enterprise capabilities to verify beyond the basics
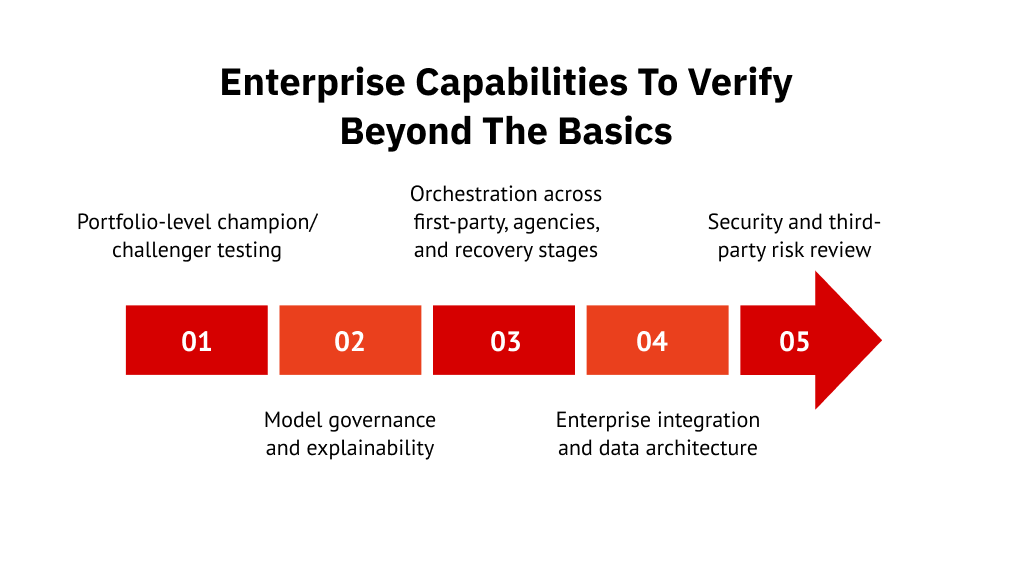
Standard sales decks cover scoring, outreach, and reporting. The capabilities below are the ones that separate enterprise-grade platforms from repackaged mid-market tools. Each includes a practical demo test you can run during evaluation.
1. Portfolio-level champion/challenger testing
A platform that cannot run controlled experiments on live accounts forces your team to guess which strategy works better. Champion/challenger testing removes that guesswork.
The platform should run competing recovery strategies on randomized account groups inside a live portfolio. It promotes the winning strategy only after the result clears a significance threshold, and it logs every promotion with an approval record.
Demo test: Ask the vendor to set up a champion/challenger test with a control group on your data. Walk through how the winning strategy gets approved and rolled out.
2. Model governance and explainability
Every account score needs reason codes that supervisors, auditors, and regulators can read. A score without a reason code is a black box that compliance cannot defend.
The platform should maintain a model inventory with documented validation schedules, ongoing performance monitoring, and a governance framework.
Demo test: Have the vendor explain, in plain language, why the model ranked three of your accounts the way it did.
3. Orchestration across first-party, agencies, and recovery stages
Enterprise programs place accounts with multiple first-party and third-party partners. The platform should set placement and recall rules for outside agencies, with performance tracked by agency.
More importantly, it should carry each consumer’s contact history, consent records, and promises-to-pay through every handoff. A consumer who opted out by SMS should be blocked from the next email and call, regardless of which team owns the account.
Demo test: Record an opt-out by SMS and confirm it blocks the next email and call. Then place an account with an agency and verify that its full history arrives intact.
4. Enterprise integration and data architecture
The platform needs to sync both ways with your loan servicing, billing, electronic health record (EHR), or customer relationship management (CRM) system through API or SFTP. One-way imports are not enough. A payment recorded in your system of record must appear in the platform, and a promise-to-pay captured on the platform must flow back.
It should also support single sign-on and keep data logically separated by legal entity.
Demo test: Update a balance in your system of record. Confirm the change appears in the platform. Then export the account in a standard format and verify every field.
5. Security and third-party risk review
At minimum, the vendor should hold a current SOC 2 Type II report and PCI DSS attestation. For patient balances, add HIPAA safeguards and a business associate agreement.
Banks and lenders face additional scrutiny under the interagency guidance on third-party risk management. That guidance lists SOC reports, PCI compliance reports, and penetration-test results as evidence to review during due diligence.
Demo test: Request the vendor’s most recent SOC 2 Type II report, PCI DSS attestation, and penetration-test summary. If they hesitate, that tells you something.
| Pro tip: Run every demo test on a sample of your own anonymized accounts, not the vendor’s demo data. Prepared datasets show a platform at its best. Your accounts show how it handles missing fields, disputed balances, and the edge cases your team deals with every day. |
How to build a vendor scorecard for enterprise procurement
A demo impression is not evidence. Enterprise buying committees need a repeatable scoring method that separates vendor polish from platform performance.
Who should sit on the evaluation committee
Include the teams responsible for operating, governing, and funding the platform:
- Collections or AR operations: recovery strategy and workflow fit
- Compliance and legal: rule enforcement, audit logs, and contractual accountability
- IT and security: integration architecture, data protection, and vendor risk review
- Finance or FP&A: business case validation and cost-to-collect projections
- Procurement: commercial terms, exit rights, and renewal structure
Scorecard criteria and method
First, separate gate criteria from scored criteria. A failed gate removes a vendor from consideration; scored criteria use evidence from demos, documentation, and the pilot.
Agree on weights before demos so presentation quality and recent impressions do not distort the results.
| Criterion | Gate or scored | Evidence source |
| Compliance and auditability | Gate | Demo test and audit log export |
| Security and certifications | Gate | SOC 2, PCI DSS, and penetration-test documents |
| Data export and exit terms | Gate | Contract language and sample export |
| Recovery lift | Scored | Pilot results against a control group |
| Integration | Scored | Demo test on your systems |
| Model governance | Scored | Demo test and model documentation |
| Omnichannel and self-service | Scored | Demo test |
| Operating support | Scored | SLAs and reference calls |
| Total cost | Scored | Full fee schedule including variable fees |
Data export and exit terms deserve gate status because they are easy to overlook during evaluation and expensive to negotiate after signing. A vendor that restricts data portability or charges punitive exit fees creates lock-in that limits your leverage at renewal.
| Pro tip: Score every vendor twice: once after the demo and once after the pilot. Give the pilot score more weight. A demo shows what a platform can do. A pilot shows what it actually does with your data, your consumers, and your compliance rules. |
How to roll out an AI debt recovery platform across a large portfolio
Selecting a platform is half the work. The other half is scaling from a single pilot to enterprise-wide deployment without disrupting live collections.
Phase-by-phase rollout plan
Give each phase a defined scope and an exit gate that must be met before expansion.
| Phase | Scope | Exit Gate |
| Pilot | One portfolio and delinquency band, tested against a randomized control group | Recovery lift holds; compliance exceptions reviewed and resolved; complaint and opt-out rates flat or lower |
| Portfolio expansion | Additional portfolios, added in order of data quality and volume | Each portfolio meets the pilot thresholds |
| Enterprise optimization | All portfolios, with ongoing champion/challenger testing and quarterly model reviews | Results hold after economic or policy changes |
At every gate, track payment-plan performance and cost to collect alongside recovery lift. Otherwise, higher recoveries can hide rising costs or falling plan completion.
Expand one portfolio at a time because data quality, consumer demographics, and regulatory requirements differ. For example, a recovery strategy that works on credit card accounts may underperform on medical or utility balances.
Change management for collectors and supervisors
AI changes what collectors do day to day. Collector roles shift toward:
- Exception handling for flagged accounts
- Hardship conversations
- Complex negotiations
Supervisors and QA staff move from sampling random calls to reviewing AI decisions and exception queues.
Put updated training and performance metrics in place before each phase goes live. A collector measured on call volume will resist a workflow that routes routine accounts to self-service. Align the metrics to the new model first.
How to build the business case for your CFO
A recovery platform pays for itself through incremental collections and lower operating costs. The challenge is proving that to a CFO who has seen vendor projections fall apart before.
Value drivers to quantify
Start with five value drivers that finance leaders already track. Each one has a measurement method that isolates the platform’s contribution from background improvement.
| Value driver | How to measure |
| Incremental recovery | Recoveries above the control group, not total collections |
| Cash acceleration | Change in average days from delinquency to payment |
| Cost to collect | Total collection cost divided by dollars collected |
| Loss rate | Change in charge-off rate for the treated segment |
| Compliance exposure | Change in complaints and contact-rule exceptions |
Incremental recovery is the number that gets the most attention, but cost to collect is often the faster win. A platform that routes routine accounts to self-service reduces agent hours per dollar collected, even before recovery rates climb.
Business case formulas
Two calculations give the CFO a clear picture of financial return:
- Net annual value = incremental recovery + operating cost savings minus platform fees, integration cost, and internal staff time
- Payback period = first-year total cost divided by monthly net value
Build the model on pilot data, not vendor projections. A pilot gives you real incremental recovery against a control group, real integration costs, and real staff time. Vendor estimates rarely account for your data quality, your consumer mix, or your compliance overhead.
First Credit Services engages consumers through digital channels from the start, so accounts resolve sooner instead of escalating into costlier late-stage collections. That early resolution is where the cost-to-collect improvement shows up in the business case.
Enterprise buying mistakes that stall AI recovery programs
Four procurement mistakes can make enterprise recovery harder to scale:
- Buying separate tools for each portfolio: Disconnected systems split consent records and contact histories. As a result, consumers may receive duplicate outreach, while audit trails become harder to reconstruct.
- Piloting on the easiest segment: Low-risk accounts can create unrealistic expectations. Instead, test a representative mix that includes older debt, disputed balances, and relevant regulatory requirements.
- Committing before the pilot ends: Signing a multi-year contract before validating results weakens your negotiating leverage. Thus, establish separate pilot terms and an approval point before the long-term commitment.
- Underfunding data cleanup: Missing contact details and duplicate records weaken scoring and outreach targeting. Fix these issues before launch so each expansion phase starts with reliable data.
Build the evidence to scale enterprise AI debt recovery
A platform earns its place when recovery gains hold as you move from one pilot to multiple portfolios.
Start with an operating model your team can sustain. Then validate capabilities on representative accounts and align stakeholders around a shared scorecard. Expand in stages, checking that recovery improvements justify the cost and operational effort at each step.
This gives your CFO a clearer investment case and your AR team a rollout it can manage.
Schedule a consultation about scaling recovery across your portfolios with managed AI.
FAQs
1. Does an AI debt recovery platform replace our collections system of record?
Not always. Many enterprises keep their system of record for account data and add an AI platform for scoring, outreach, and self-service payments. The right choice depends on how flexible your current system is. Either way, data must sync both ways, so every team works from the same balance and status.
2. How long does a propensity model need to learn a new portfolio?
It depends on the volume and quality of historical payment and contact data available. With limited history, platforms typically start with rule-based treatment and retrain as outcomes build up.
3. What happens to active payment plans when we switch platforms?
Active plans, schedules, and settlement terms must move with each account. Recurring payment authorizations may need reconfirmation with the new payment processor. Map these steps in the data migration plan so no consumer misses a scheduled payment or gets contacted about a balance already under an agreement.
4. Can AI recovery platforms handle Spanish and other non-English outreach?
Many platforms support multilingual messaging and payment portals. Have native speakers and your compliance team review translated templates before launch. Also confirm that AI voice or chat agents handle language switching and escalation to a bilingual collector correctly.
5. How do AI platforms handle bankruptcy, deceased, and litigation accounts?
AI platforms should flag these accounts and pause automated outreach until their status has been reviewed. They should check account records for relevant updates, suppress inappropriate collection activity, and route flagged accounts to a specialist for review. This is particularly important for bankruptcy accounts, as contacting a consumer or pursuing collection activity in violation of the automatic stay can create serious legal risks.
6. Is there a minimum portfolio size for an enterprise AI recovery platform to pay off?
There is no fixed threshold. Licensed software carries fixed costs that need enough volume to justify them, while contingency-based managed services lower that bar because fees track recoveries. Run the payback formula from the business case section on your own volumes and recovery rates before deciding.